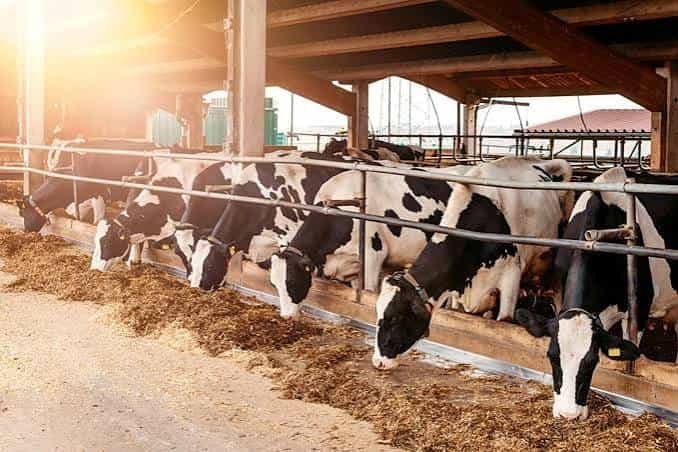
Starting a dairy farm can require a substantial initial investment. The farmer has to arrange money not only for cows or buffaloes but also for a cattle shed, milking equipment, fodder storage, insurance, water facilities and working capital. For a new entrepreneur, financing all these expenses from savings may not be practical.
Several banks provide dairy farm loans, but the phrase “dairy loan with government subsidy” often creates confusion. There is no single universal dairy subsidy under which every farmer automatically gets 25% or 33% of the cost of cows. The old Dairy Entrepreneurship Development Scheme (DEDS), which is still mentioned on many websites, was discontinued from 2020-21.
At present, farmers need to choose the right scheme according to the type of dairy project. For a new small dairy enterprise, PMEGP can be one of the important credit-linked subsidy options because animal-husbandry activities such as dairy are permitted. Larger dairy-processing projects have different support under schemes such as AHIDF, while State Governments may operate their own cattle and dairy subsidy programmes.
Here is how the present system works and how an applicant can approach a dairy farm loan with government support.
Which Government Scheme Gives Subsidy for a Dairy Farm?
For an individual planning a new dairy unit, Prime Minister’s Employment Generation Programme (PMEGP) is an important option to examine.
KVIC has specifically clarified that animal-husbandry activities including dairy, poultry, aquaculture and piggery are allowed under PMEGP. Such projects are treated under the service sector, and the cost of livestock such as cattle can be considered as capital expenditure based on applicable NABARD unit costs.
Under the current PMEGP structure, the maximum eligible project cost for a business/service enterprise is ₹20 lakh.
PMEGP Subsidy for Dairy Farm
The PMEGP subsidy depends on the applicant’s category and whether the dairy unit is in a rural or urban area.
| Category | Own Contribution | Urban Subsidy | Rural Subsidy |
| General Category | 10% | 15% | 25% |
| Special Category | 5% | 25% | 35% |
Special-category applicants include eligible SC, ST, OBC, women, minorities, ex-servicemen, persons with disabilities and certain other notified categories.
Dairy Loan Subsidy Example
Suppose a general-category applicant establishes an eligible dairy farm in a rural area with a total approved project cost of ₹10 lakh.
The broad structure would be:
- Applicant contribution: ₹1 lakh
- Bank finance: up to ₹9 lakh
- Eligible PMEGP subsidy at 25%: ₹2.50 lakh
The ₹2.50 lakh is not given to the farmer as cash immediately. It is kept under the prescribed margin-money mechanism and later adjusted against the loan after completion of the lock-in period and fulfilment of scheme conditions.
Who Can Apply for a PMEGP Dairy Farm Loan?
For a new dairy project, an individual applicant should generally meet these conditions:
- Applicant must be above 18 years of age.
- There is no general income ceiling.
- The dairy enterprise should be a new project.
- For a service-sector project costing above ₹5 lakh, the applicant should have passed at least Class VIII.
- The applicant should not have already received government subsidy for the same existing unit.
- Only one person from one family can normally obtain PMEGP assistance for setting up a new enterprise.
For PMEGP purposes, family includes the applicant, spouse and unmarried children.
What Expenses Can Be Included in a Dairy Farm Project?
A properly prepared dairy project can contain several eligible components.
Depending on bank and scheme approval, the project may include:
- Purchase of cows or buffaloes
- Construction or eligible cost of cattle shed
- Milking equipment
- Chaff cutter
- Fodder storage arrangement
- Water facilities
- Milk cans and basic dairy equipment
- Animal insurance
- Equipment required for handling milk
- Initial working-capital requirement
For PMEGP animal-husbandry projects, the cost of livestock can be included in capital expenditure, but it should be based on reasonable rates such as the applicable NABARD unit cost for the State.
The cost of purchasing land itself is generally not included in eligible PMEGP project cost.
How To Get a Dairy Farm Loan With Subsidy Step By Step
Step 1: Decide the Size of Your Dairy Farm
First determine whether you want to start with:
- 2 to 4 animals
- 5 to 10 animals
- 10 to 20 animals
- A larger commercial dairy operation
Do not choose the number of cattle simply according to the maximum loan available. The project should match your available land, fodder supply, labour, water and local milk market.
Step 2: Prepare a Dairy Farm Project Report
A good Detailed Project Report or DPR is one of the most important parts of the loan application.
It should explain:
- Number and breed of animals
- Expected cost per animal
- Milk yield assumptions
- Expected selling price of milk
- Cattle shed cost
- Feed and fodder expenses
- Veterinary expenses
- Labour cost
- Insurance
- Equipment cost
- Working capital
- Expected monthly income
- Operating expenses
- Profit estimate
- Loan repayment capacity
Avoid unrealistic assumptions such as every animal producing the same quantity of milk throughout the year.
The bank wants to know whether the dairy can generate sufficient income after feed, veterinary and other operating costs.
Step 3: Arrange Your Own Contribution
Under PMEGP, the applicant must bring part of the project cost.
The minimum contribution is generally:
- 10% for general-category applicants
- 5% for special-category applicants
For a ₹12 lakh dairy project, for example, a general-category applicant should be prepared to contribute at least ₹1.20 lakh.
The applicant should not depend entirely on the subsidy to meet the initial cost.
Step 4: Apply Through the PMEGP Portal
Applications for PMEGP can be submitted through the official PMEGP e-Portal.
The applicant has to provide information such as:
- Aadhaar
- PAN
- Personal details
- Educational qualification
- Category
- Proposed dairy location
- Project cost
- Employment generation
- Preferred financing bank
- Project report
- Required certificates
The current PMEGP portal remains operational and records PMEGP assistance during FY 2026-27.
Step 5: Select the Bank Carefully
Choose a bank branch that handles agricultural, MSME or PMEGP lending and is reasonably close to the proposed dairy unit.
Possible lenders can include:
- Public sector banks
- Regional Rural Banks
- Cooperative banks where participating
- Other participating scheduled banks
Submitting a PMEGP application does not guarantee bank sanction. The financing bank independently examines the project.
Step 6: Bank Appraisal of the Dairy Project
The bank can examine:
- Applicant’s credit history
- Existing loans
- Availability of shed and land
- Fodder arrangements
- Water supply
- Proposed cattle breed
- Milk marketing arrangement
- Cost of animals
- Expected milk production
- Applicant contribution
- Repayment capacity
A confirmed milk buyer, cooperative society or nearby collection centre can strengthen the practical viability of a dairy proposal.
Step 7: Complete Training and Loan Formalities
PMEGP beneficiaries may have to complete the prescribed Entrepreneurship Development Programme or related training.
The bank will also complete documentation, security requirements, insurance and other sanction formalities.
The applicant then deposits the required own contribution.
Step 8: Purchase Animals After Loan Sanction
Farmers should avoid buying all animals before receiving the bank’s sanction unless specifically advised otherwise.
After sanction, cattle should normally be purchased according to the approved project and bank procedure.
The bank may require:
- Veterinary health certificate
- Identification/tagging of animals
- Purchase receipt
- Insurance
- Seller details
Buying healthy, productive animals is more important than simply choosing the cheapest cattle available.
How Is the Government Subsidy Adjusted?
PMEGP is a back-ended margin money subsidy.
The subsidy is not normally transferred to the applicant for personal use. It is kept with the financing bank under the prescribed arrangement.
The normal lock-in period is three years. After the required period, successful physical verification and fulfilment of PMEGP conditions, the eligible subsidy is adjusted against the loan account.
Therefore, applicants should plan loan repayment without assuming that the subsidy will be immediately available as cash.
Is There a NABARD Dairy Farm Subsidy?
Farmers frequently search for a “NABARD dairy subsidy of 25% or 33.33%.” Much of this information relates to the old Dairy Entrepreneurship Development Scheme.
DEDS was discontinued from FY 2020-21. Farmers should therefore not pay consultants who promise automatic DEDS subsidy for purchasing cows or buffaloes today.
NABARD continues to play an important role in agricultural and rural finance, including preparation of indicative unit costs, but this should not be confused with the discontinued DEDS subsidy.
What Is AHIDF for Dairy Businesses?
The Animal Husbandry Infrastructure Development Fund (AHIDF) is another important Central Government programme, but it serves a different purpose.
It supports eligible investments such as:
- Dairy processing
- Milk value-addition facilities
- Animal feed plants
- Breed-improvement infrastructure
- Animal waste-to-wealth projects
- Other approved animal-husbandry infrastructure
Eligible entities can obtain term loans of up to 90% of eligible project cost, and the Central Government provides 3% interest subvention. The scheme also provides credit-guarantee support for eligible MSMEs.
AHIDF should therefore not be described as a simple subsidy scheme for an individual wanting to purchase two or four milch cows.
Kisan Credit Card for Dairy Farmers
Dairy farmers can also use the Kisan Credit Card facility for working-capital requirements.
KCC can help meet recurring costs such as:
- Cattle feed
- Veterinary treatment
- Medicines
- Labour
- Electricity
- Water
- Other routine dairy expenses
The Department of Animal Husbandry and Dairying continues to promote KCC access for eligible dairy farmers.
However, KCC working-capital finance and a capital subsidy for establishing a dairy farm are different benefits.
State Government Dairy Subsidy Schemes
Several States also operate their own dairy-development, livestock-distribution or self-employment schemes.
Assistance can vary according to:
- State
- Farmer category
- Number of animals
- Breed
- Women or SHG status
- SC/ST status
- District
- Annual budget allocation
A farmer should therefore check with the District Animal Husbandry Office, State Dairy Development Department or local bank before applying.
State assistance may sometimes be more suitable than a Central scheme for a small cattle-purchase project.
Common Reasons Dairy Loans Are Rejected
A dairy loan can be refused because of:
- Poor CIBIL or repayment history
- Unrealistic milk-yield assumptions
- Insufficient fodder availability
- No proper cattle shed
- Lack of own contribution
- Excessive project cost
- Incomplete documents
- No reliable milk market
- Existing overdue loans
- Applicant having little understanding of dairy management
A realistic five-animal dairy project with assured fodder and milk marketing may be more bankable than an oversized 20-animal proposal prepared only to maximise subsidy.
Conclusion
A dairy farm loan with government support is possible, but applicants must choose the correct scheme. For a new small dairy enterprise, PMEGP can provide margin-money subsidy, while AHIDF mainly supports larger dairy infrastructure and processing projects. Always verify current Central and State schemes before purchasing animals or paying any agent.